E-Way Bill for Ecommerce Sellers: When Needed and How to Generate from an Order
Most ecommerce parcels are under the e-way bill threshold, which is why the one order that crosses it gets missed. Here is when an online seller needs an e-way bill, who generates it when a courier or marketplace moves the goods, and how to raise one from the invoice.
On this page
Key takeaways
- An e-way bill is required when the consignment value in a single invoice exceeds Rs 50,000 for inter-state movement; several states set a higher limit for intra-state movement, so check your state's notification.
- The registered seller generates Part A from the invoice; Part B carries the vehicle or transporter details and can be filled by the courier, which is how most ecommerce shipments work.
- Validity is one day for every 200 km or part of it, counted from the time Part B is first filled, and can be extended before expiry or within the grace period after it.
- Returns and RTO parcels moving back above the threshold need their own e-way bill, referenced to the credit note or delivery challan, not the original invoice.
An ecommerce seller needs an e-way bill when the value of a single consignment exceeds Rs 50,000 and the goods move by road, rail, air or ship, whether to a customer in another state, to a marketplace warehouse, or back to you as a return. The seller, as the registered consignor, generates Part A from the invoice; the courier fills Part B with the vehicle or transporter details; and the bill is valid for one day per 200 km from the moment Part B is filled.
Most online orders are well under Rs 50,000, which is exactly why the rule gets missed. A seller shipping phone cases never thinks about it, and then ships one bulk B2B order or one high-value item without a bill, and the parcel is detained at a checkpost with a penalty on the tax involved. This guide sets out when the bill is needed, who is responsible when a courier or marketplace is moving the goods, what Part A and Part B contain, how to generate one from an order, and how returns are handled. The rules themselves are covered in the e-way bill guide; this post is about applying them to an ecommerce operation.
When an ecommerce seller needs an e-way bill
Rule 138 requires an e-way bill before the movement of goods when the consignment value exceeds Rs 50,000. Four details decide whether an order crosses the line.
- Consignment value is the value on the invoice including GST, but excluding the value of any exempt goods on the same invoice. A Rs 45,000 taxable item at 18 percent is a Rs 53,100 consignment.
- The threshold applies per invoice, per conveyance. Two orders of Rs 30,000 each to different customers do not add up, but a single invoice covering both does.
- The Rs 50,000 limit applies to inter-state movement everywhere. For intra-state movement several states have set a higher limit, Rs 1 lakh in a number of them, and some exempt certain goods; check your state's notification on the GST portal before relying on a higher figure.
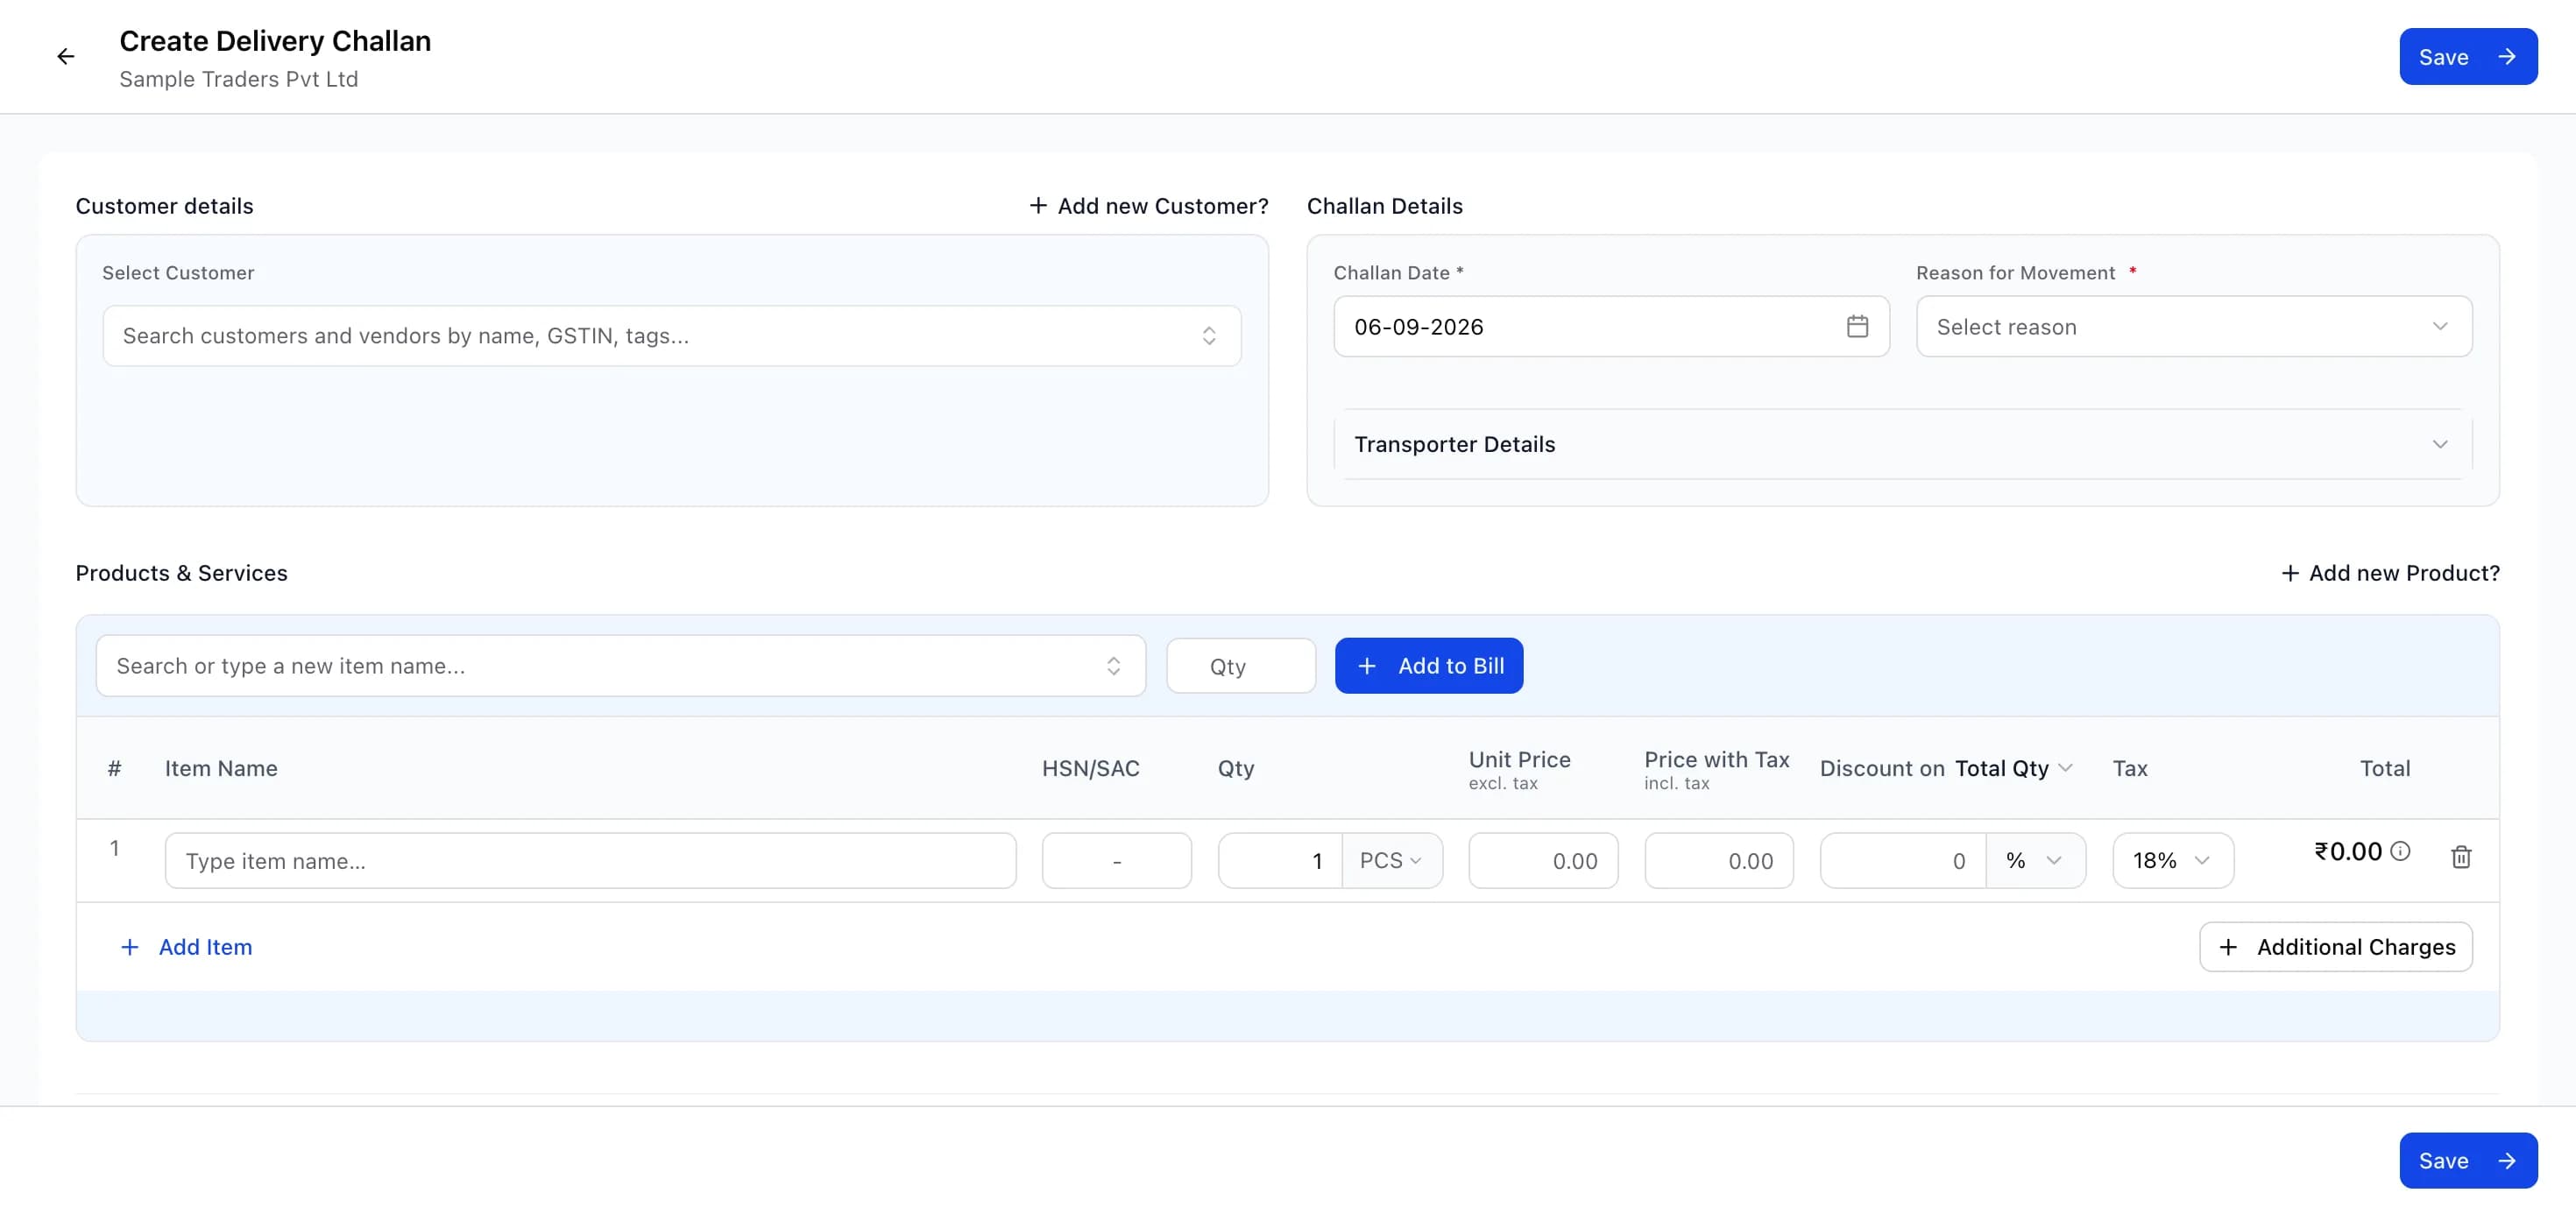
- Movement includes stock transfers to a marketplace fulfilment centre or your own warehouse in another state, on a delivery challan, even though no sale has happened.
Some movements are exempt regardless of value: goods listed in the exemption annexure, transport by non-motorised conveyance, and movement from a port or airport to an inland container depot for customs clearance, among others. Ordinary courier shipments of taxable goods are not exempt.
Shipping charges and add-ons can push an order over the line
A Rs 48,000 item with Rs 1,500 shipping and 18 percent GST is a consignment of over Rs 58,000. Check the total invoice value including tax and shipping, not the product price, before deciding no bill is needed.
Who generates it: seller, courier or marketplace
Rule 138 puts the obligation on the registered person causing the movement, which for an outward supply is the seller. In practice ecommerce shipments involve three parties, and the rule allows the work to be shared.
Who generates the e-way bill in each ecommerce shipping model
| Shipping model | Part A | Part B | What to confirm |
|---|---|---|---|
| Self-ship through a courier aggregator | Seller, from the invoice | Courier, using its transporter ID | The courier's transporter ID is in your master and it updates Part B on every vehicle change |
| Marketplace logistics (Amazon, Flipkart) | Marketplace or its logistics arm, on your authorisation | Same | Written confirmation that they generate it, and where you can download the bill |
| Own vehicle to a local hub | Seller | Seller, with vehicle number | Part B before the vehicle leaves |
| Stock transfer to a fulfilment centre | Seller, against a delivery challan | Transporter | Delivery challan value and the correct sub-type |
| Return or RTO leg | Courier or seller, against a credit note or challan | Courier | Who raises it, and that the parties are reversed |
When an e-commerce operator or a courier agency moves the goods, Rule 138 allows them to furnish Part A on the seller's behalf if authorised. Marketplaces usually do this for orders shipped through their own logistics. For self-ship orders through an aggregator, the seller generates Part A and the courier updates Part B, so the seller needs the courier's transporter ID and a process that generates the bill before the pickup, not after.
Whoever generates it, the seller is the one whose goods get detained. Confirm the arrangement in writing and check the first few high-value shipments yourself.
Part A and Part B explained
An e-way bill has two parts. Part A is the description of the consignment, filled from the invoice. Part B is the description of the transport, filled when the vehicle is known.
Part A carries the GSTIN of the supplier and recipient (URP for an unregistered customer), the place of dispatch and delivery with PIN codes, the document type, number and date, the HSN of the goods, the value, the tax split, the reason for transport and the approximate distance. Once Part A is submitted the portal issues a unique e-way bill number, but the bill is not valid for movement until Part B is filled.
Part B carries the mode of transport, the vehicle number for road, or the transport document number for rail, air or ship, and the transporter ID where a transporter is involved. Part B can be updated any number of times as the consignment changes vehicles, by the transporter or the seller. Distance is now largely auto-calculated from the PIN codes, with a small allowance above the calculated figure.
For a consignor to transporter movement within the state of under 50 km, Part B is not required for that leg; it becomes required when the transporter moves the goods onward. The delivery challan guide covers the document used when goods move without a sale.
Validity, extension and cancellation
Validity starts when Part B is first filled and runs one day for every 200 km or part of it for normal cargo, ending at midnight of the last day. A 210 km shipment gets two days. Over-dimensional cargo gets one day per 20 km. Multimodal shipments with at least one leg by ship follow the same 200 km rule.
Extension is possible when the goods cannot reach the destination in time, because of a breakdown, a diversion or a delay in transhipment. It must be done before expiry or within the grace period after expiry that the rules allow, by the generator or the current transporter, with the reason recorded. Cancellation is possible within 24 hours of generation if the goods have not moved, and not at all once the bill has been verified in transit. The recipient can reject a bill within 72 hours of it becoming visible to them, or on delivery if earlier.
Verification of an expired bill in transit attracts detention, a penalty on the tax involved and the release procedure under Section 129. Setting the generation step at pickup, not at order, and choosing the right distance avoids most expiries.
Generating an e-way bill from an order, step by step
The fastest path is from the invoice, because Part A is the invoice restated. The steps below are generic; a billing system that generates e-way bills through the NIC API from the invoice screen collapses them into one action.
- Create the tax invoice for the order in your billing system, with the customer's full address and PIN code, the HSN and rate on each line, and shipping as a line item.
- Check the invoice value including tax against the threshold for the movement: Rs 50,000 inter-state, your state's limit intra-state.
- From the invoice, start the e-way bill. Transaction type is outward, sub-type supply for a sale or others with a delivery challan for a stock transfer.
- Confirm the consignor (you) and consignee. For an unregistered customer, enter URP with the name, address, state and PIN from the invoice.
- Confirm the dispatch address if it differs from your registered address, which it does when goods leave a warehouse.
- Check the HSN, quantity, taxable value and tax on each line. These come from the invoice; correct the invoice, not the bill, if they are wrong.
- Enter the transporter ID for the courier or aggregator and the approximate distance, or accept the PIN-based distance.
- Submit Part A. Record the e-way bill number on the invoice and share it with the courier.
- Have the courier update Part B with the vehicle number at pickup, or enter it yourself for your own vehicle. Validity starts now.
- Print or attach the bill to the consignment along with the invoice.
Billing software connected to the NIC API does steps 3 to 8 from the invoice in one click and stores the bill number on the invoice. Bulk JSON upload on the portal is the alternative for a batch of B2B orders. The GST invoice format guide covers the invoice fields the bill depends on.
Before you submit Part A
- Invoice value including tax and shipping checked against the threshold for this movement
- Customer address, state and PIN code complete; URP for an unregistered buyer
- Dispatch-from address is the warehouse the goods actually leave from
- HSN on every line valid in the portal master
- Transporter ID for the courier saved in the master
- Sub-type correct: supply for a sale, others with a delivery challan for a stock transfer
- Distance realistic for the route; validity will be set from it
Returns, RTO and replacement shipments
Goods coming back to you above the threshold need their own e-way bill, and the original bill does not cover the return leg. The underlying document is the credit note you issue for the return, or a delivery challan if the credit note is issued later, with the sub-type set to sales return. The parties are reversed: the customer or the courier hub is the consignor, entered as URP for an unregistered customer, and you are the consignee.
For RTO parcels, the courier is holding the goods and usually generates the return bill under its own transporter ID; confirm this in your courier agreement, and check that the bill references your credit note or challan so the two records tie together. For customer returns picked up from the customer, the same applies.
A replacement shipment is a fresh outward movement on a new invoice and needs its own bill if above the threshold. Do not reuse the original order's bill for the replacement. The credit note and debit note guide covers the document that sits behind the return bill.
Multiple invoices in one parcel
When several invoices to the same customer travel in one consignment, generate one e-way bill per invoice above the threshold and let the transporter combine them into a consolidated e-way bill for the vehicle. An invoice below the threshold in the same parcel does not need its own bill, but the consignment as a whole is still checked against the bills that exist.
Errors that get parcels detained
Most detentions trace to one of a short list of mistakes, all avoidable at the generation step.
- No bill because the product price was checked instead of the invoice value with tax and shipping.
- Expired bill because it was generated at order time and the courier picked up two days later.
- Part B never filled, so the bill was never valid for movement.
- Wrong dispatch address, showing the registered office when the goods left a warehouse in another state, which also puts the wrong GSTIN on the bill.
- HSN not in the portal master, so the bill could not be generated and the parcel went without one.
- Vehicle changed at a hub without Part B being updated.
- Return leg shipped on the original bill.
Each of these is a process fix. Generate at pickup from the invoice, keep the courier's transporter ID in the master, check the value with tax, and treat every return above the threshold as a new movement.
Billing software that generates the e-way bill through the NIC API from the invoice, stores the bill number on it, and raises the return bill from the linked credit note keeps all of this in one record. myBillPlease does this with e-way bill generation via the NIC API alongside its invoices and credit notes, and the free plan covers up to 100 invoices a month.
The threshold is the only judgment call. Once an order crosses it, the process is mechanical: invoice, Part A, transporter, Part B, ship, and a fresh bill for anything that comes back.
Frequently asked questions
- Do ecommerce sellers need an e-way bill for every order?
- No. An e-way bill is needed only when the consignment value in one invoice exceeds Rs 50,000 and the goods move by motorised transport.
- Who generates the e-way bill when a courier ships my order?
- The registered seller, as consignor, generates Part A from the invoice. Part B, the vehicle or transporter details, can be filled by the courier using its transporter ID.
- Is an e-way bill needed for a B2C order to an unregistered customer?
- Yes, if the value crosses the threshold. The consignee is entered as URP (unregistered person) with the customer's name, address and state from the invoice.
- How long is an e-way bill valid?
- One day for every 200 km or part of it for normal cargo, counted from the time Part B is first entered. A 650 km shipment gets four days.
- Can I cancel an e-way bill if the order is cancelled?
- Yes, within 24 hours of generation, provided the goods have not moved and it has not been verified in transit.
- Do I need an e-way bill for a customer return or an RTO parcel?
- If the return consignment exceeds the threshold, yes.